

By Paula Reed Ward
The Tribune-Review, Greensburg
(TNS)
Oct. 1 — Accusations that Pittsburgh misrepresented financial information when providing it to potential bond investors could spur an investigation by federal regulators, harm the city’s ability to borrow in the future and shake investor confidence, experts said.
Pittsburgh attorney Chad Ostrosky, who has been practicing securities law for 10 years, sees risk for the city from whistleblower allegations of Securities and Exchange Commission violations.
“It could give the SEC a basis to go after the city if they misstated the financial condition of the city and the revenue,” Ostrosky told TribLive.
The Allegheny County District Attorney’s Office is investigating potential bid-rigging under the Gainey administration. It served a warrant on the city in March.
In the warrant, Dan Friedson, a former City Council solicitor, alleged city officials knowingly provided “improper financial information” that painted an overly rosy picture of Pittsburgh’s finances as they wooed investors. Investigators said Friedson claimed SEC violations “with every bond issuance.”
Armed with civil authority, any SEC investigation would likely take years and potentially impact the city’s ability to issue bonds in the future, experts said.
While the SEC cannot forbid Pittsburgh officials from issuing bonds, any findings that show they violated the law in the past could impact investor confidence moving forward.
“It’s meaningful to investors and the future of any kind of bond grading,” Ostrosky said. “I certainly think it could affect investor confidence.”
Jeff Cox, a former SEC enforcement attorney now in private practice in Florida, said violations can have consequences long after the case is over.
“The immediate practical issue is credibility in the bond market,” Cox said. “Municipal bond issues rely heavily on investor confidence.
“Future bond offerings could be more difficult.”
Bonds are a critical tool used by Pittsburgh to raise money for capital projects.
A spokesperson for the SEC declined to comment. A spokesman for the U.S. Attorney’s Office in Pittsburgh also declined to comment.
City Controller Rachael Heisler and council last year slammed the final budget proposed by the former mayor, Ed Gainey. Heisler derided it as “not an honest document.” Council rejected Gainey’s budget and rewrote the spending plan.
Gainey’s successor, Mayor Corey O’Connor, in March disclosed a budget shortfall he said could be as much as $40 million and blamed “a lot of false assumptions” by the Gainey administration.
Friedson claimed the city overestimated its revenue from real estate taxes and wrongly included revenue from the so-called “jock tax” on athletes and performers—”violations when presenting financials for bond issuances,” according to the search warrant.
Pittsburgh City Councilwoman Erika Strassburger, who chairs council’s finance and law committee, is paying close attention. She said she wants to ensure the city continues to have the ability to issue bonds moving forward.
“I intend to investigate whether the public release of this warrant and the contents within it will play any role in a future bond issuance or the ability to maintain our financial strength with regard to credit ratings,” Strassburger said.
No intent required
According to the search warrant, Friedson went to the district attorney’s office with concerns about financial irregularities during the Gainey administration, alleging potential bid-rigging but also violations of what are known as Generally Acceptable Accounting Principles.
Those principles, Cox said, promote transparency, consistency and comparability.
“They allow investors and others to evaluate a municipality’s financial condition,” he said. “(They) provide a common language so investors, auditors, rating agencies and taxpayers can understand and compare financial reporting.”
However, a departure from those principles alone, Cox said, does not establish a violation of the law.
Friedson told investigators that he believed city officials were violating SEC law in how they issued bonds.
“The Real Estate Taxes were not accounting for the decline in revenues that were known to the City of Pittsburgh,” the affidavit said. “The ‘Jock Tax’ was being included in budgeted revenues but the tax was not itemized and was being hidden for those that would review the City of Pittsburgh’s finances.”
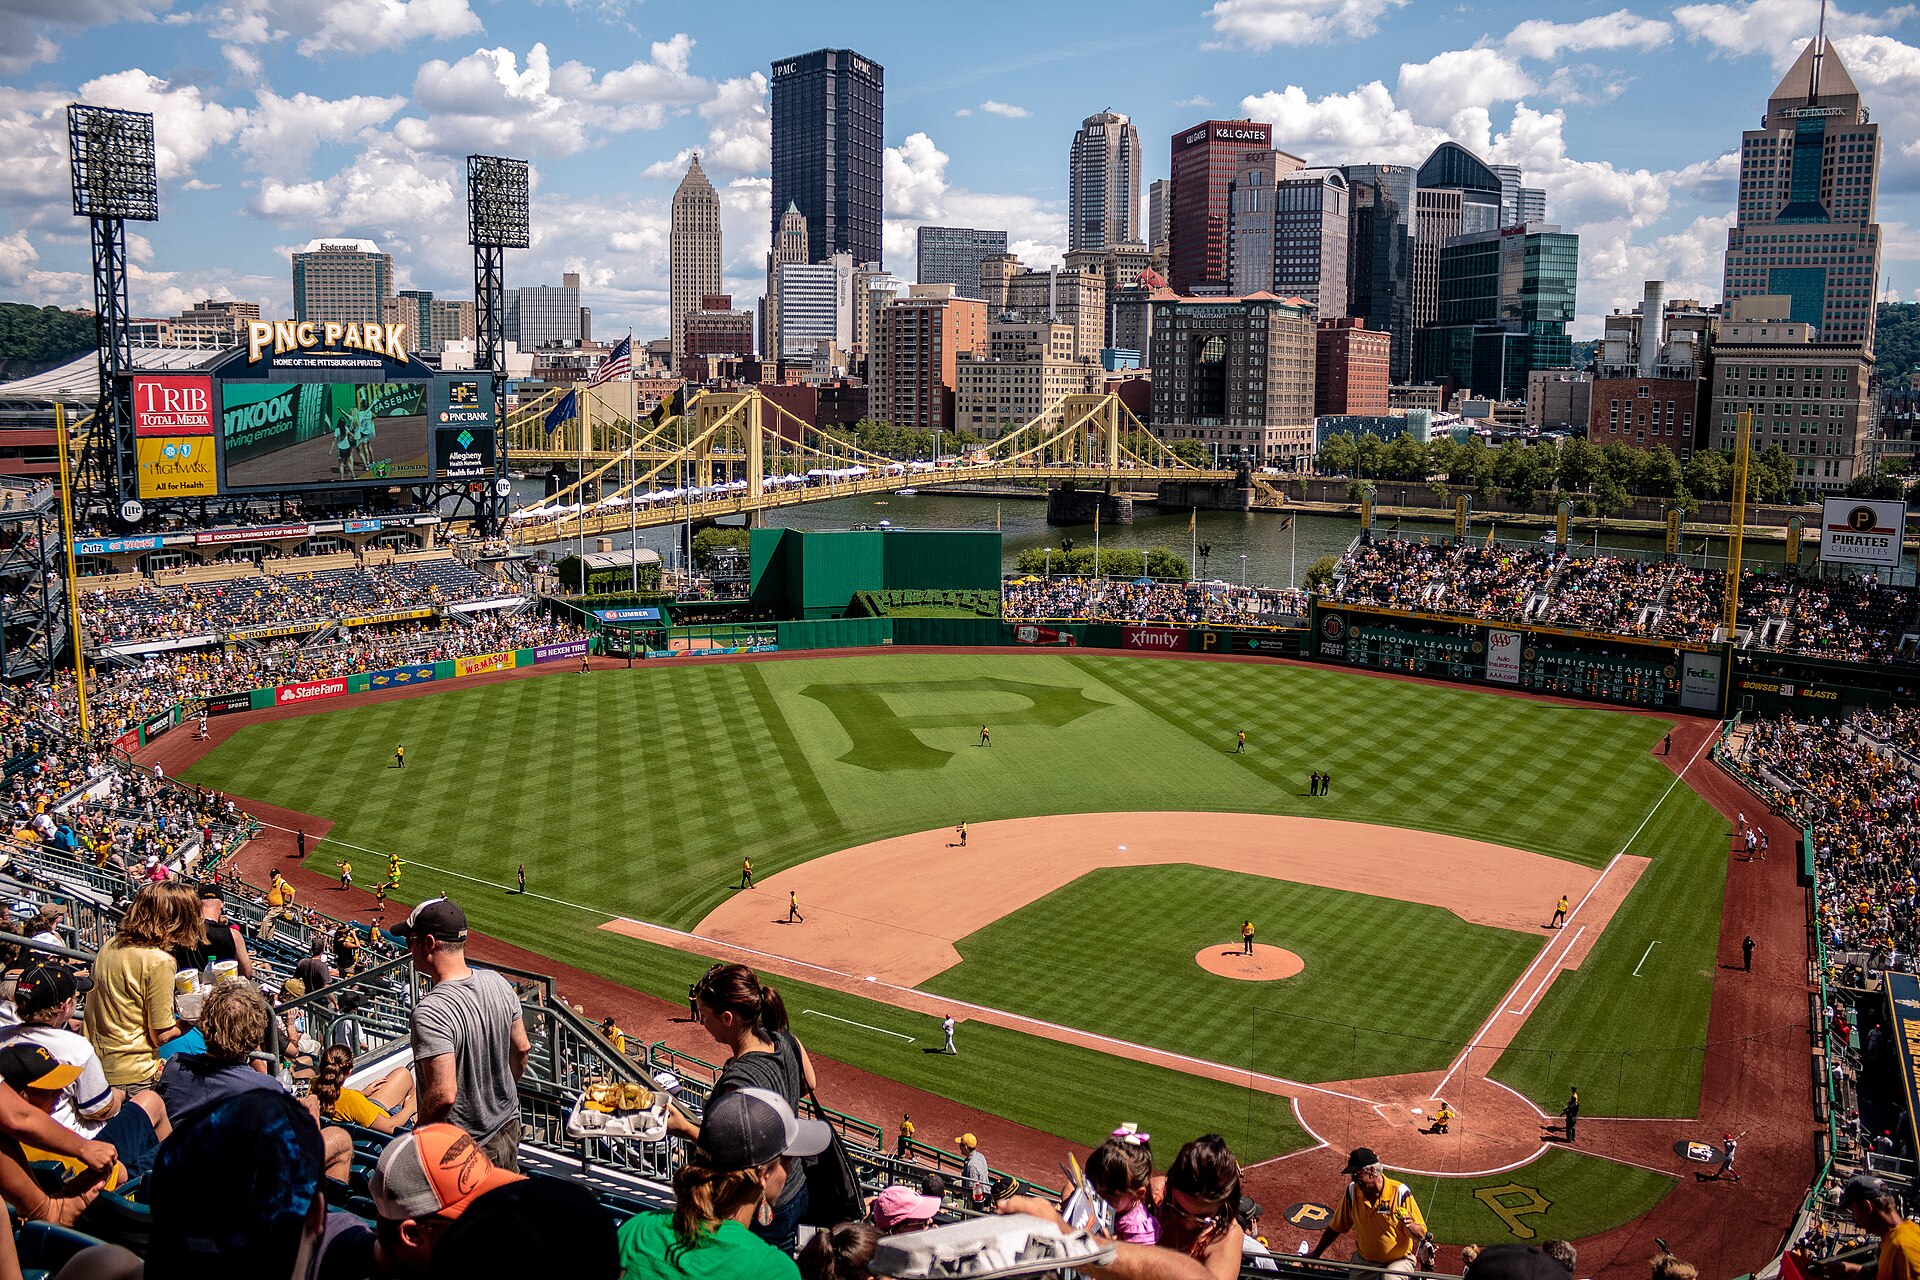
The “jock tax,” formally known as the Sports Facility Usage Fee, assessed a 3% surcharge on income from non- Pittsburgh residents when they performed at the city’s publicly funded stadiums. Over the years, it raised $79 million.
However, it had already been overturned by the state Commonwealth Court and has since been struck down by the Pennsylvania Supreme Court for being an unconstitutional violation of the state’s Uniformity Clause.
Recommended Articles
Cox, the Florida attorney, said the bedrock of most SEC municipal investigations is disclosure.
“It’s disclosure—not whether the city made a bad prediction,” he said. “The question is whether the information provided to bond investors was materially accurate.”
Cox said that the city including the jock tax as revenue in and of itself is not necessarily a violation. But he questions whether officials were clear to investors that that stream of revenue could disappear given the adverse opinion they’d already gotten from the Commonwealth Court.
Ostrosky, the Pittsburgh lawyer, said “if they knew this revenue isn’t coming in, and they didn’t disclose that, that could be an SEC violation.”
There is no intent requirement, he continued.
“Even if it’s a mistake or oversight, that doesn’t remedy the rule violation,” Ostrosky said. “It can be negligence.”
Nicholas J. Guiliano, a securities attorney based in Philadelphia, agreed.
“It doesn’t matter if it was done with fraudulent intent or not,” he said. “If it’s wrong, it’s wrong, it’s wrong.”
Who knew what when
Under the federal code, it is illegal for any person “to make any untrue statement of a material fact or to omit to state a material fact necessary” in connection with the purchase or sale of a security.
The key word in the regulation, Cox said, is “material.”
What did the city’s disclosures—or omissions—mean in the broader scheme of how reliable their numbers were for revenue, deficits and debt service, Cox asked.
“It all comes down to who knew what when and whether that information, if material, was exposed to bond investors,” Cox said. “What was discussed internally and how that compares to what bond investors were told.”
According to SEC guidance, “The omission or misstatement of an item in a financial report is material if, in the light of surrounding circumstances, the magnitude of the item is such that it is probable that the judgment of a reasonable person relying upon the report would have been changed or influenced by the inclusion or correction of the item.”
The biggest source of funding for Pittsburgh’s $112.3 million capital budget—which pays for large projects like bridge repairs, recreation center upgrades and renovations at public safety facilities—is bond money. The 2026 capital budget included over $51 million of it.
At the end of 2025, Pittsburgh had $512 million in outstanding debt.
Each year, the city takes out a bond to cover such capital projects. This year, the city is budgeted to spend over $78 million paying back such debt.
Bond ratings
The three major bond rating agencies have given Pittsburgh’s debt generally strong ratings.
As of May, prior to the information in the search warrant being made public, Fitch Ratings assigned Pittsburgh an “AA” rating—near the top of its scale—for a $56 million capital improvement bond with a rating outlook of stable.
S&P Global Ratings gave Pittsburgh’s bond an “AA-” long-term rating, also with a stable outlook, and also among the agency’s highest ratings.
According to a city spokesman, the Moody’s rating is Aa3, three rungs below the highest score, also with a stable outlook.
None of the rating agencies responded to messages seeking comment.
George Dougherty, who teaches public administration and public policy at the University of Pittsburgh, said it’s possible an SEC finding against the city could impact its bond ratings in the very short term.
“Could it make it more expensive to issue debt? Sure, as it probably should,” Dougherty said. “But in the long run, if they have fixed their process, an organization that big will have its stuff together and bounce back.”
What would likely result, Dougherty said, is that investors would perform additional due diligence before agreeing to do business with the city — including potentially obtaining third-party audits.
As for ratings agencies, he continued, they would likely do the same.
One way the city could protect itself, Dougherty said, is by getting out in front of the issue.
City leaders, for instance, could tout the new mayoral administration and proclaim they took the whistleblower’s concerns seriously. They could publicly discuss how they’ve reformed their internal processes and announce that they’ve fixed any problems, according to Dougherty.
“The markets presume you have people in place who know what they’re doing,” Dougherty said. “So systematic mistakes aren’t really all that different from the nefarious.
“It’s the same type of internal process failures that lead to both.”
Possible consequences
While the SEC has only civil authority, the U.S. Justice Department could run a tandem criminal investigation into a municipality and its officials, experts said.
A federal criminal probe, Guiliano said, might look at mail fraud, wire fraud and potential kickbacks.
Based solely on reading the the affidavit supporting the DA’s search warrant, Ostrosky said in Pittsburgh’s case, “It doesn’t seem like there’s any ill-gotten gains stemming from the bond issuance.”
Typically, he continued, the SEC is more likely to investigate if there are losses to investors stemming from any misrepresentations.
Nothing like that has been reported thus far stemming from the Pittsburgh probe.
If the city were found to have committed an SEC violation, potential penalties could include the issuance of a cease and desist order—basically the federal government ordering a municipality to stop breaking the law—as well as civil penalties such as fines.
In that case, Ostrosky said, city taxpayers would be on the hook.
Guiliano said it is rare for any monetary penalty against a municipality to be more than $100,000.
The SEC can also enjoin individuals who work in an administration from participating in any bond offerings in the future.
But Guiliano said federal regulators can’t stop a municipality from continuing to issue securities.
But when they do, they must disclose the SEC findings of fact against them.
“Investors consider that,” Guiliano said. “It goes to the trustworthiness of the financial information.
“It matters because it looks bad.”
Photo credit: Yuhan Du/Unsplash
_______
© 2026 The Tribune-Review (Greensburg, Pa.). Visit www.triblive.com. Distributed by Tribune Content Agency LLC.
Sign in to get access to this free resource, and all of our whitepapers and reports.

Download this content today!
Register Now Already registered? Click here to Log In