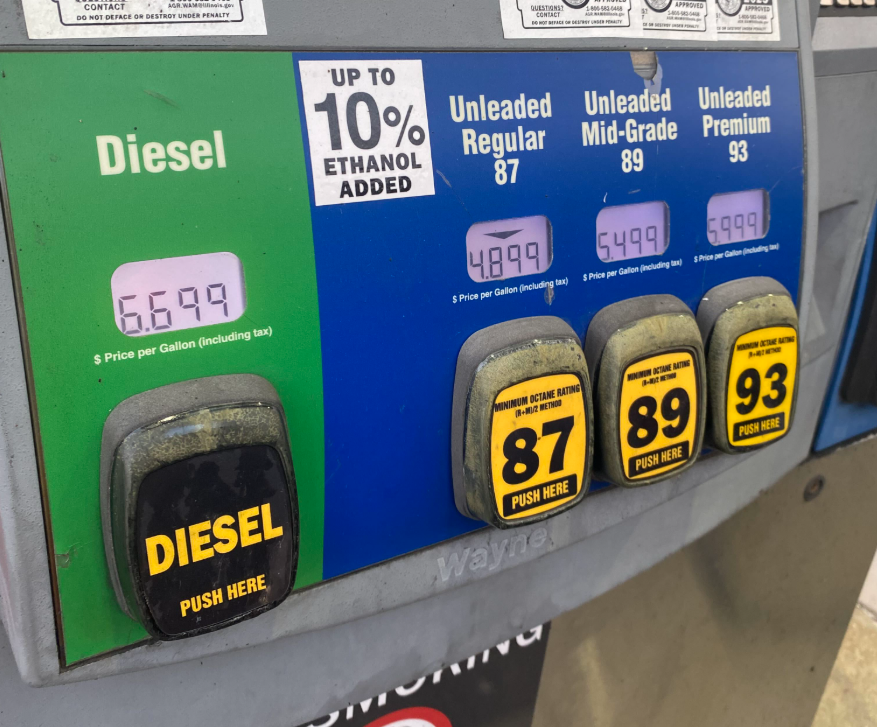


The IRS announced Wednesday evening that it’s temporarily suspending federal tax penalties when dyed diesel fuel is sold for use or used on highways nationwide.
The relief is retroactive to Oct. 1, 2026, and will remain in effect until Dec. 31, 2026. The IRS said in an Oct. 14 media release that relief is available to “any person who sells dyed diesel fuel or uses dyed diesel fuel for highway use.”
The move is in response to an executive order signed by President Donald Trump on Oct. 5 that aims to lower costs for diesel users by making dyed diesel more accessible through the end of the year.
The executive order allows dyed diesel to be used for on-road purposes temporarily and defers federal taxes on the fuel with no penalties and no interest through the end of the year. The order also directs the secretary of the Treasury, together with the secretary of Defense, to explore ways to eliminate the obligation to pay deferred taxes.
Ordinarily, dyed diesel fuel isn’t subject to tax because it’s destined for an exempt use, such as use on a farm for farming purposes; however, it would be taxed if sold for highway use or used to power a vehicle on the highway, the IRS says. Generally, the person liable for the tax is the person who sells dyed diesel fuel at retail or, if the dyed diesel fuel isn’t purchased at retail, the operator of the motor vehicle (e.g., dyed diesel fuel held in a storage tank on a farm).
Diesel used for off-road purposes, such as agricultural, construction, or heating, is dyed red to help law enforcement identify it.
Recommended Articles
During the relief period, the IRS says ordinary procedures for collection and enforcement will be suspended. All IRS fuel compliance officers will be re-assigned other responsibilities, and no federal inspections of on-road dyed fuel usage will occur. Taxpayers don’t need to maintain records necessary to substantiate their eligibility for relief during the relief period, according to the IRS.
The tax agency says it won’t impose any penalties related to the excise tax for dyed diesel fuel sold for use or used in diesel-powered vehicles on highways nationwide during the relief period. This relief includes penalties for failure to make semimonthly deposits of tax or to maintain adequate records. Sellers and distributors are under no obligation to investigate or document the ultimate end-use of dyed fuel sold during the relief period, the IRS says.
Taxpayers who believe they qualify for relief but receive a penalty notice should follow the instructions in the notice or contact the IRS for assistance, the media release states.
The IRS says it expects to issue further guidance on the tax postponement and will consider other options to eliminate the obligation to pay any amounts deferred. Forthcoming IRS guidance will detail how this relief applies to Form 720, Quarterly Federal Excise Tax Return, and any other relevant forms.
The IRS reiterated that this relief only applies for federal tax purposes, and it has no effect on state fuel taxes and penalties that a state may impose on the use of dyed diesel fuel on the highway. Many, but not all, states have provided similar state excise tax-related relief. The IRS says it encourages taxpayers to refer to their applicable state agencies for the latest guidance on state-level relief.
Sign in to get access to this free resource, and all of our whitepapers and reports.

Download this content today!
Register Now Already registered? Click here to Log In