Following its first-ever request for public comment on standard setting this past June, the Public Company Accounting Oversight Board this week updated its standard-setting, research, and rulemaking agendas.
The PCAOB says the updated agendas reflect its current priorities and the feedback from stakeholders that the board received during the comment period.
Recommended Articles
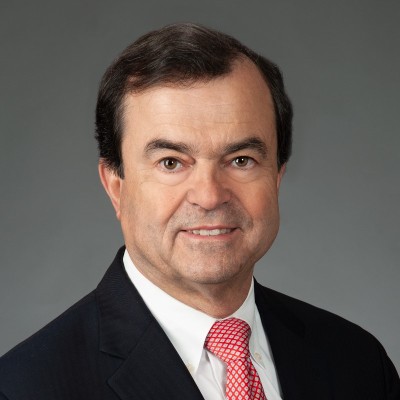
“Feedback from investors, auditors, academics, and other stakeholders is critical for the PCAOB to fulfill our mission. In this case, it helped inform our updated standard-setting, research, and rulemaking agendas and assisted us in refining our priorities,” PCAOB Chairman Demetrios Logothetis said in a statement on Sept. 30. “Under these updated agendas, we will continue to focus our efforts on projects that are practical, responsive to today’s capital markets, and ultimately, advance audit quality and investor protection.”
The standard-setting agenda includes projects that address the topics of negative assurance related to comfort letter engagements, auditor independence, fraud, noncompliance with laws and regulations, and going concern.
The research agenda includes projects on data and technology, firm and engagement performance metrics, and communications with audit committees. The updated agendas also include a rulemaking project on a permanent broker-dealer inspection program.
QC 1000 amendments
The PCAOB also highlighted its most recently completed standard-setting project: amendments to the audit regulator’s new quality control standard, QC 1000, A Firm’s System of Quality Control, which goes into effect on Dec. 15 of this year.
The amendments, approved on Sept. 9, improve alignment, where appropriate, with other quality management standards and seek to reduce compliance costs without compromising the PCAOB’s statutory mission to protect investors and further the public interest in the preparation of informative, accurate, and independent audit reports, the board said in a statement.
Recommended Articles
The amendments to QC 1000 will:
- Rescind the “design-only” requirement so that QC 1000 imposes requirements only on accounting firms that are required to comply with applicable professional and legal requirements with respect to any “engagement”;
- Provide increased flexibility in filling certain specified roles in the quality control system by permitting roles to be assigned to non-firm personnel and divided among multiple individuals;
- Rescind the requirement to have an external quality control function;
- Narrow and simplify communication requirements relating to metrics that the firm communicates to external parties about its audit practice, firm personnel, or engagements;
- With respect to identified engagement deficiencies, require evaluation of whether similar engagement deficiencies exist on other engagements only if the identified deficiency resulted or could result in a failure to obtain sufficient appropriate evidence to support the conclusion reached on an engagement or an inappropriate overall conclusion on the subject matter of an engagement;
- Revise the definition of quality control deficiency to make clear that, when firms have implemented more than one quality response to address the same quality risk, they can take those other quality responses, such as compensating responses, into account when determining whether a deficiency exists;
- Allow firms to select the date in which they annually evaluate the effectiveness of their quality control system, rather than requiring firms to evaluate as of Sept. 30;
- Revise the quality control system evaluation conclusions to align more closely with the conclusions in other quality management standards while retaining a structured process, including specified factors for consideration, to guide the evaluation; and
- Simplify the requirements for retention of quality control system documentation and abbreviate the retention period from seven to five years.
The amendments adopted by the board last month won’t change the Dec. 15 effective date and are subject to approval by the Securities and Exchange Commission.
Photo credit: Public Company Accounting Oversight Board/Flickr
Sign in to get access to this free resource, and all of our whitepapers and reports.

Download this content today!
Register Now Already registered? Click here to Log In
Tags: Accounting, Auditing, auditing standards, PCAOB, quality control