

There are upcoming vacancies on the Public Company Accounting Oversight Board’s Investor Advisory Group and Standards and Emerging Issues Advisory Group that the audit regulator is hoping to fill before the end of the year.
According to the PCAOB, certain members’ terms expire on Dec. 31, 2026. Appointed members would serve from Jan. 1, 2027, to Dec. 31, 2028. The deadline for submissions to fill those vacancies is Dec. 14, 2026.
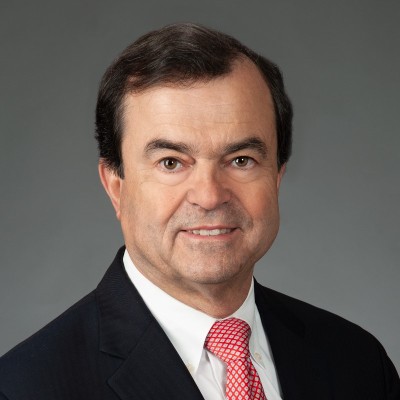
“The PCAOB functions best when informed by the perspectives of the full audit and financial reporting ecosystem: investors, audit committee members, preparers, auditors, academics, and others who rely on high-quality, independent audits,” PCAOB Chairman Demetrios Logothetis said in a statement. “The IAG and SEIAG are a crucial part of the PCAOB’s stakeholder engagement, and we look forward to receiving nominations from those interested in being a part of them.”
The IAG’s objective is to provide the board with the views of investors and their advocates on the PCAOB’s regulatory agenda, including:
- Advising the board regarding matters related to the auditing profession of concern to investors;
- Providing the board with investors’ perspectives on current regulatory issues; and
- Serving as a source of information, views, perspectives and recommendations to the board on other matters regarding the PCAOB’s oversight activities from the point of view of investors.
According to the PCAOB, the SEIAG advises the board on existing standards, proposed standards, potential new standards, and on matters other than standards, such as emerging issues, that are of significance to the PCAOB in order to protect the interests of investors and further the public interest in the preparation of informative, accurate, and independent audit reports.
The IAG Charter and the SEIAG Charter contain information about membership selection, qualifications, terms, and ethical obligations of members of the PCAOB’s advisory groups.
Individuals can nominate themselves or others for service on one or both advisory groups.
- Self-nominations: Individuals interested in nominating themselves for IAG or SEIAG service should submit a letter of interest describing their relevant experience and qualifications, along with a current résumé or curriculum vitae, to advisorygroups@pcaobus.org. Candidates interested in applying for both advisory groups should note that in their letter of interest.
- Nominating others: Those seeking to nominate others for consideration to the IAG and/or the SEIAG should submit letters of recommendation to advisorygroups@pcaobus.org. Letters of recommendation should address the candidate’s relevant experience and qualifications.
More information about the PCAOB’s advisory groups can be found here. Questions regarding the nomination process can be sent to advisorygroups@pcaobus.org.
Photo credit: Public Company Accounting Oversight Board/Flickr
Sign in to get access to this free resource, and all of our whitepapers and reports.

Download this content today!
Register Now Already registered? Click here to Log In