

The IRS issued guidance on Tuesday that extends tax relief for farmers and ranchers in 49 states and other regions who sold or exchanged livestock because of drought conditions.
Under the guidance, those affected may take more time to replace their livestock and defer tax on any gains from the forced sales or exchanges.
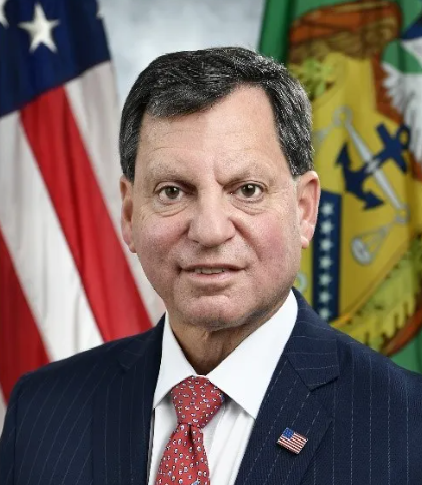
“Large swaths of the United States continue to experience drought conditions, distressing hard-working American farmers and ranchers,” IRS CEO Frank Bisignano said in a statement. “By extending relief for those who sell or exchange livestock, the IRS is providing much needed support to those who feed our nation.”
Notice 2026-54 lists the specified areas, by county or other jurisdiction, that qualify for federal assistance. The list includes 49 states, the District of Columbia, Puerto Rico, and other areas that reported exceptional, extreme, or severe drought during the 12-month period ending on Aug. 31, 2026. Alaska is the only state not included on the list.
The tax relief generally applies to capital gains realized by eligible farmers and ranchers from sales or exchanges of livestock held for draft, dairy, or breeding purposes. Sales of other livestock—such as those raised for slaughter or held for sporting purposes—and sales of poultry don’t qualify.
Recommended Articles
Eligible farmers and ranchers must show that drought prompted the sales or exchanges, and that the area received a federal drought designation. Generally, livestock must be replaced within a four-year period, instead of the usual two-year period. The IRS is authorized to further extend this replacement period if the drought persists.
The replacement period extension announced in the notice gives eligible farmers and ranchers until the end of their first tax year after the first drought-free year after the four-year replacement period to replace the sold or exchanged livestock. As a result, eligible farmers and ranchers whose drought-sale replacement period was scheduled to expire at the end of 2026 will have until the end of their next tax year to replace the sold or exchanged livestock.
The IRS provides this extension to eligible farmers and ranchers if the applicable region is listed as suffering exceptional, extreme, or severe drought conditions during any week between Sept. 1, 2025, and Aug. 31, 2026. This determination is made by the National Drought Mitigation Center.
Details and an example of how this provision works can be found in Notice 2006-82, available on IRS.gov.
More information on reporting drought sales and other farm-related tax issues can be found in Publication 225, Farmer’s Tax Guide, available on IRS.gov.
Sign in to get access to this free resource, and all of our whitepapers and reports.

Download this content today!
Register Now Already registered? Click here to Log In